 AnyTime News

Anytime News Network
Pooja Srivastava
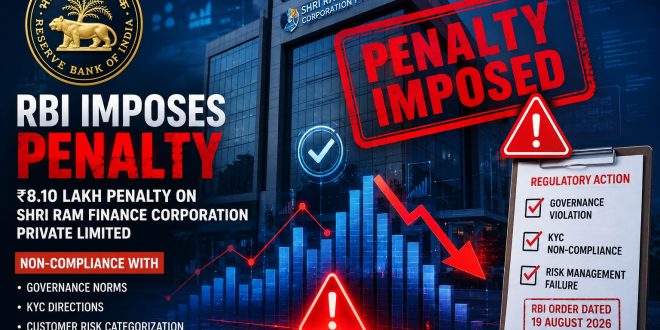
Upholding strict financial governance and consumer protection standards, the Reserve Bank of India (RBI) has cracked the whip on non-compliant financial institutions. By an order dated August 19, 2026, the central bank slapped a monetary penalty of ₹8.10 lakh on Shri Ram Finance Corporation Private Limited for flagrant violations of regulatory directions concerning ‘Governance’ and ‘Know Your Customer (KYC)’ norms.
The penalty was enacted under the powers conferred upon the RBI by the Reserve Bank of India Act, 1934. A statutory inspection of the company, assessing its financial position as of March 31, 2025, brought severe supervisory lapses to light. Following the inspection, a show-cause notice was served to the company demanding an explanation for its failure to adhere to mandated guidelines.
After meticulously evaluating the company’s written replies and personal submissions during hearings, the RBI sustained the following major charges:
Unauthorized Management Changes: The company appointed a director—resulting in a turnover of more than 30 percent of its board members (excluding independent directors)—without securing prior written permission from the RBI.
Failure in Risk Categorization: The institution neglected to establish a robust system for classifying its customers into low, medium, and high-risk categories.
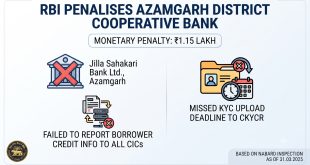
Delayed CKYC Uploads: The firm failed to upload mandatory customer KYC records onto the Central KYC Records Registry (CKYCR) within the stipulated timelines.
The central bank emphasized that this punitive action stems purely from regulatory non-compliance and does not invalidate existing customer agreements. However, it serves as a stern warning that laxity in governance and anti-money laundering (KYC) protocols will invite severe regulatory repercussions.